
A Practical Guide to Credit Cards
Credit cards can be useful financial tools when you understand how they work. They can help with everyday purchases, provide payment flexibility and in some cases offer rewards or other benefits.
At the same time, interest charges, fees, missed payments and high balances can make credit expensive. That is why understanding the basics is an important part of responsible credit management.
Our credit card guides break complicated topics into straightforward explanations so you can better understand APR, credit utilization, credit scores, rewards, fees, balance transfers and other important concepts.
Credit Card Basics: A Beginner's Guide
Understand how credit cards work, how statements and payments work, what APR means and how to use a card responsibly.
Read the Guide →Understand the Fundamentals
Before comparing credit cards or rewards programs, it helps to understand the basic mechanics of credit. These guides cover the concepts you are most likely to encounter.
Credit Card Basics
Learn the essential concepts behind credit cards, statements, payments, interest and balances.
Read More →
APR vs. Interest Rate
Understand the difference between an interest rate and APR and why the distinction matters.
Read More →
Credit Card Fees
Learn about common credit card fees and what to review before applying for a card.
Read More →Build and Maintain Healthy Credit Habits
Your credit history can affect how lenders evaluate applications for credit. Understanding the factors that influence your credit profile can help you make more informed financial decisions.
Credit Score Basics
Learn what a credit score is and the major factors that can influence it.
Read More →
How to Improve Your Credit Score
Explore practical habits that can help you manage credit more responsibly over time.
Read More →
How to Build Credit
Learn practical ways to establish and manage a stronger credit history.
Read More →Understand Your Credit Card Balances
How much of your available revolving credit you use is an important concept to understand. These guides explain utilization and practical ways to manage balances.
Credit Utilization Ratio
Understand credit utilization and why it is an important part of credit management.
Read More →
Credit Card Minimum Payments
Learn how minimum payments work and why paying only the minimum can extend repayment.
Read More →Compare Different Types of Credit Cards
Different cards are designed for different situations. Understanding the basic differences can make it easier to evaluate whether a particular type fits your needs.
Secured vs. Unsecured Credit Cards
Compare the basic differences between secured and unsecured credit cards.
Read More →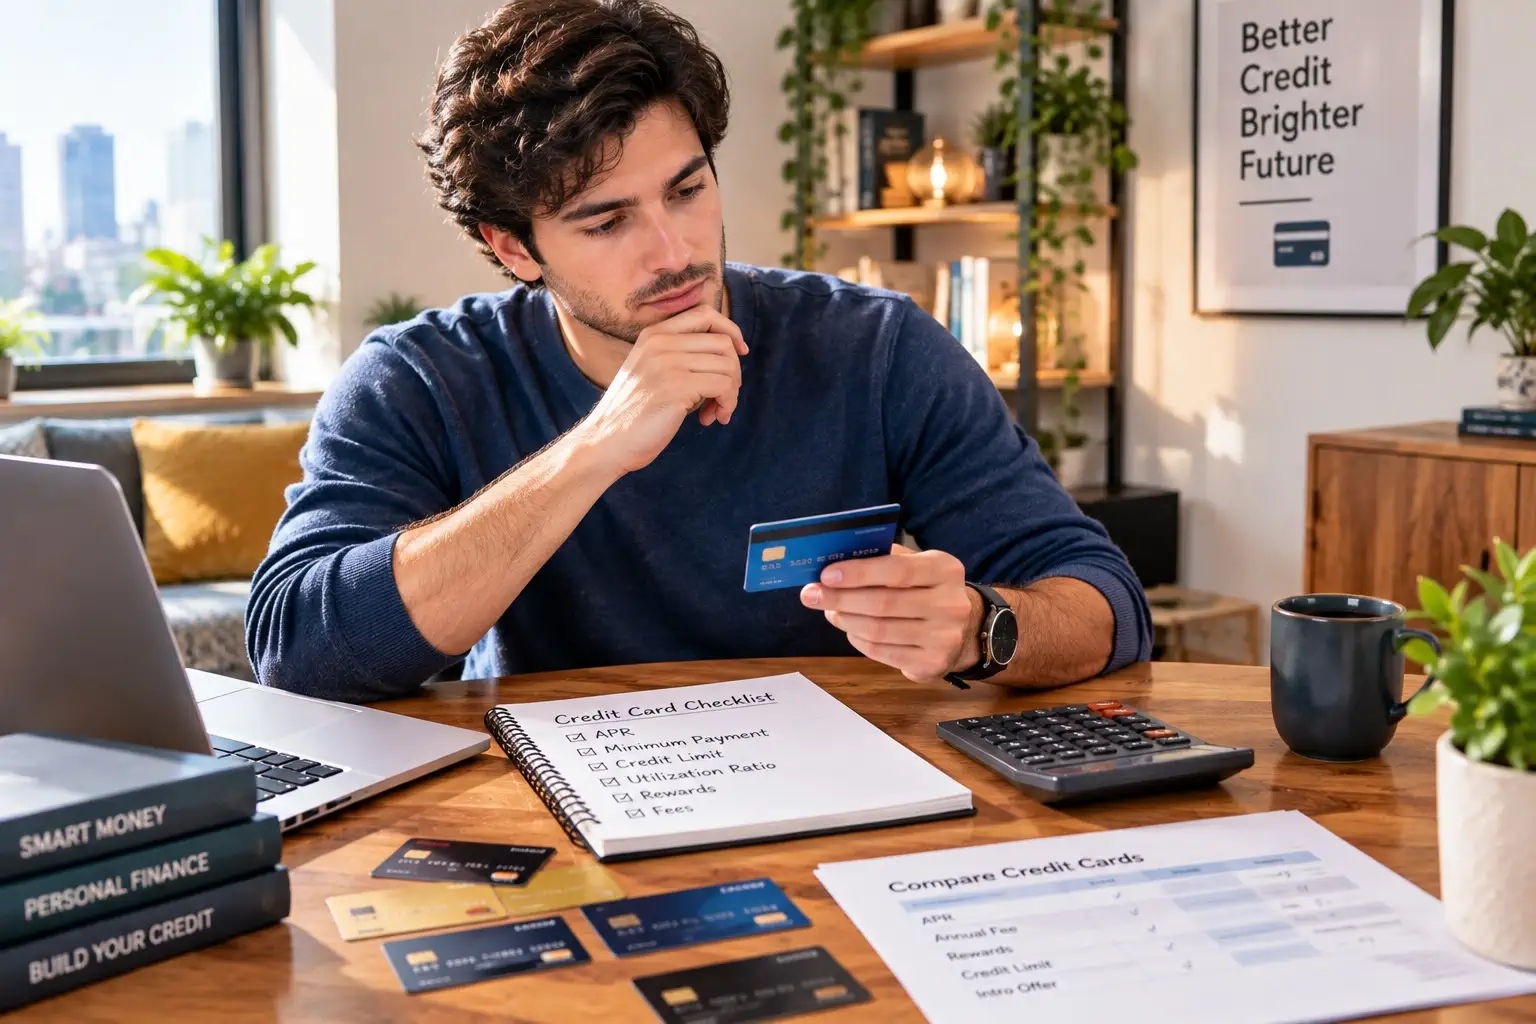
Credit Card Rewards Explained
Understand points, cash back, rewards structures and important terms to review.
Read More →
How to Choose a Credit Card
Learn which card features and costs are worth comparing before applying.
Read More →Balance Transfers and Credit Card Debt
Balance transfer offers can have important terms and conditions. Before using one, it is useful to understand introductory APRs, transfer fees, repayment timelines and what happens after a promotional period ends.
Balance Transfer Credit Cards
Learn how balance transfers work, including introductory APRs, transfer fees and repayment considerations.
Read More →A Practical Credit Card Framework
You do not need to understand every credit card product at once. Start with a few simple principles and build from there.
Know the Cost
Review APRs, annual fees, late fees, transfer fees and other costs before applying.
Pay on Time
Build a reliable payment routine and understand your statement due dates.
Watch Balances
Keep spending aligned with your budget rather than treating available credit as extra income.
Review Regularly
Check statements, transactions, fees and your overall credit strategy periodically.
Before Applying for a Credit Card
Consider these questions before submitting an application:
- What is the card's annual fee?
- What APR applies to purchases?
- Are there introductory APR terms?
- Are there balance transfer or cash advance fees?
- How does the rewards program work?
- Are there spending requirements for promotional rewards?
- Does the card fit your existing budget?
- Can you comfortably manage the payments?
- What happens after any introductory period ends?
Remember
A credit card is a financial product, not additional income. The right choice depends on your own financial situation, spending habits, repayment ability and the terms offered by the card issuer.
Credit Card Questions
What is a credit card?
A credit card is a payment account that allows you to borrow money from a card issuer to make purchases, subject to the account's terms and credit limit. The balance may be paid according to the issuer's payment requirements and interest may apply to balances that are not paid according to the account terms.
What does APR mean?
APR stands for annual percentage rate. For credit cards, it is commonly used to describe the annualized cost of borrowing, although the exact terms and calculations can vary by account.
What is credit utilization?
Credit utilization generally refers to the amount of revolving credit being used compared with the available credit limit. It is one of the factors commonly considered in credit scoring models.
Should I pay my credit card balance in full?
Paying the statement balance in full by the due date can help you avoid interest on purchases when your card's terms provide a grace period. Always review the specific terms of your account.
Are credit card rewards always worth it?
Rewards should be considered alongside annual fees, spending requirements, interest rates, redemption rules and your normal spending habits. Rewards generally should not be a reason to spend beyond your budget.
Use Credit With a Clear Plan
Understanding credit cards can make everyday financial decisions easier. Start by learning the basics, review the costs of any card you consider and keep your credit activity connected to a realistic budget.
Whether you are learning about credit scores, comparing rewards, understanding APR or managing an existing balance, the goal is the same: make decisions based on clear information rather than assumptions.
Explore the guides below to continue learning about credit cards and personal finance.
More Credit Card Guides