Building credit takes time but the basic principles are relatively simple: use credit responsibly, make payments on time, keep track of your accounts and avoid taking on debt you cannot comfortably manage.
A strong credit history can be useful when applying for financial products and services. Depending on the situation, credit information may also be considered by lenders, landlords, insurers or other businesses.
If you are starting with little or no credit history, you do not necessarily need a complicated strategy. Consistent financial habits can help establish a credit profile over time.
There is no guaranteed shortcut to building strong credit. Credit scoring models can use different information and your results may vary depending on your individual credit history and the scoring model being used.
What Is Credit?
Credit generally refers to your ability to borrow money or obtain goods and services with an agreement to pay later.
When you use a credit card, the card issuer may extend a line of credit that you can use for purchases.
Your payment history and other information about your credit accounts can become part of your credit history.
Over time, this information may be used by credit scoring models to calculate credit scores.
What Is a Credit History?
Your credit history is a record of information associated with your borrowing and credit accounts.
Depending on the account and reporting system, information can include items such as:
- Payment history
- Account balances
- Credit limits
- Account age
- Types of credit accounts
- Credit applications and inquiries
Different credit reporting agencies and scoring models can use different information, so there is not one universal credit score that applies to every situation.
Why Does Credit Matter?
Credit history can affect how lenders evaluate applications for certain financial products.
Depending on the lender and situation, credit information may influence:
- Whether you qualify for certain credit products
- The interest rate you may be offered
- The credit limit you receive
- The terms of certain financial products
Requirements vary between lenders, products and jurisdictions.
1. Check Your Credit Reports
If you already have credit accounts, one useful first step is understanding what information is being reported about you.
Review your credit reports for:
- Accounts you recognize
- Correct payment information
- Accurate balances
- Correct personal information
- Accounts you did not authorize
If you find information that appears inaccurate, follow the applicable dispute process with the relevant credit reporting agency or creditor.
Do not assume that a credit score alone tells the entire story. Reviewing the underlying credit report can help you understand what information may be affecting your credit profile.
2. Consider a Secured Credit Card
A secured credit card may be an option for people who have limited or no credit history, depending on the issuer and their eligibility.
Secured cards typically require a refundable security deposit that can serve as collateral for the account.
Before applying, review:
- Annual fees
- Interest rates
- Security deposit requirements
- Credit reporting practices
- Upgrade or graduation options
The goal should be responsible credit use rather than spending more simply to build credit.
3. Consider Becoming an Authorized User
Some credit card issuers allow an existing cardholder to add another person as an authorized user.
Depending on the issuer and reporting practices, information from the account may potentially appear on the authorized user's credit reports.
If someone is considering adding you to their account, both people should understand the account's payment history, balance, fees and reporting practices first.
Being an authorized user does not guarantee a particular credit score increase.
4. Make Every Payment on Time
Payment history is an important part of many credit scoring systems.
One of the simplest habits you can develop is paying your credit obligations by their due dates.
Consider setting up:
- Automatic payments
- Calendar reminders
- Account alerts
- Regular account reviews
If you use automatic payments, make sure enough money is available in the linked account to cover the payment.
A credit card should fit within your budget. Building credit is not a reason to spend money you cannot afford to repay.
5. Manage Your Credit Utilization
Credit utilization generally refers to the amount of revolving credit you are using compared with your available revolving credit limits.
For example, if a credit card has a $2,000 limit and a $500 balance, the balance represents 25% of that credit limit.
| Credit Limit | Example Balance | Utilization |
|---|---|---|
| $1,000 | $100 | 10% |
| $2,000 | $500 | 25% |
| $5,000 | $1,000 | 20% |
Credit scoring models can consider revolving balances in different ways. Keeping balances manageable can therefore be an important part of responsible credit use.
You should not carry interest-bearing debt simply to improve your credit score.
6. Avoid Opening Too Many Accounts at Once
Applying for multiple credit accounts within a short period can create several challenges.
Each application may involve a credit inquiry, depending on the product and issuer.
Opening multiple accounts can also make it harder to keep track of balances, due dates, fees and spending.
Instead of applying for every available offer, focus on choosing financial products that fit your actual needs.
7. Be Careful About Closing Old Accounts
Closing a credit card can change your available credit and potentially affect aspects of your credit profile.
Before closing an account, review:
- Annual fees
- Available credit
- Account age
- Current balances
- Rewards or benefits
- The issuer's account policies
There is no universal rule that every old account should remain open. Consider the costs and potential effects before making the decision.
8. Monitor Your Credit Regularly
Credit monitoring can help you identify changes or unfamiliar activity.
When reviewing your credit information, look for:
- Unexpected accounts
- Unfamiliar inquiries
- Incorrect balances
- Incorrect payment history
- Personal information errors
Early detection can make it easier to investigate potential errors or unauthorized activity.
Common Credit-Building Mistakes
Carrying a balance just to build credit
You generally do not need to pay interest on a credit card balance simply to establish a credit history.
Paying late
Missed or late payments can potentially harm your credit history, depending on how and when they are reported.
Maxing out credit cards
High revolving balances can create financial pressure and may affect credit scoring factors.
Applying for too many cards
More accounts are not automatically better. Applying for products you do not need can create unnecessary complexity.
Ignoring credit reports
Errors can go unnoticed when you never review your credit information.
Spending beyond your budget
Credit should be a payment tool, not an excuse to spend more than you can afford.
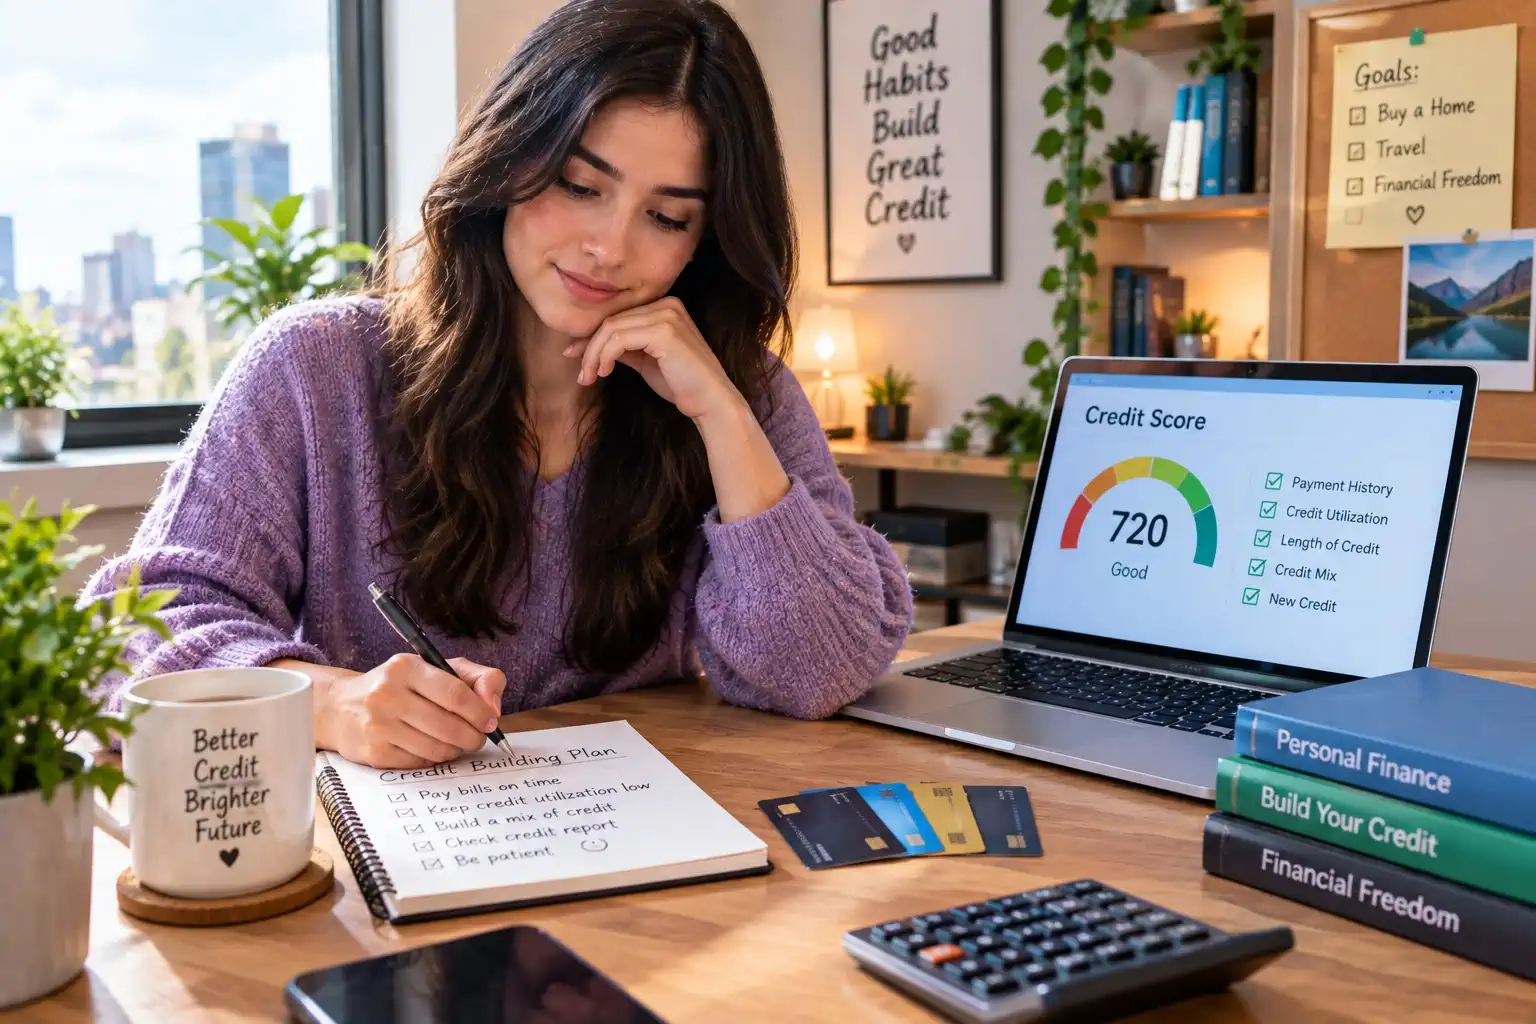
A Simple Credit-Building Plan
If you are starting from scratch, keep the process simple.
| Step | Action |
|---|---|
| 1 | Review your existing credit information. |
| 2 | Choose a credit product that fits your situation. |
| 3 | Use only a manageable amount of available credit. |
| 4 | Make payments by the due date. |
| 5 | Monitor your accounts and credit reports. |
| 6 | Give your credit history time to develop. |
The most important part of this process is consistency. Credit history generally develops over time rather than overnight.
Learn the Basics Before Choosing a Card
If you are new to credit cards, it can help to understand terms such as APR, minimum payment, credit limit, fees and grace periods before applying for a card.
Read our beginner-friendly guide: Credit Card Basics: A Beginner's Guide .
You can also learn more about credit utilization and how it relates to revolving credit.
Final Thoughts
Building credit is primarily about developing consistent, responsible financial habits.
Start by understanding your credit reports, choosing appropriate accounts, paying on time, keeping balances manageable and monitoring your information.
Avoid chasing quick fixes or taking on debt simply because you believe it will improve your credit. A sustainable approach is generally easier to maintain.
Most importantly, remember that credit is only one part of your overall financial picture. A healthy financial plan should also include budgeting, emergency savings, debt management and long-term goals.
Borrow responsibly, pay on time, understand your accounts and give your credit history time to develop.
More Credit Card Guides