Choosing a credit card can feel complicated because cards often advertise different rewards, fees, interest rates, introductory offers and benefits. The right way to compare them is not to look for a card that sounds impressive but to find one whose costs and features match how you actually use credit.
A card that works well for one person may be a poor fit for someone else. Your spending patterns, credit history, payment habits, financial goals and willingness to pay an annual fee can all affect which type of card makes sense.
In This Guide
- Start With Your Credit Card Goal
- Understand Your Credit Profile
- Review Your Spending Habits
- Understand Different Types of Credit Cards
- Compare APR
- Check the Annual Fee
- Compare Rewards
- Review Other Fees
- Evaluate Introductory Offers
- Consider the Credit Limit
- Compare Cards Side by Side
- Common Credit Card Selection Mistakes
- Credit Card Selection Checklist
- Frequently Asked Questions
Start With Your Credit Card Goal
Before comparing individual cards, decide what you want the credit card to accomplish.
Someone who wants to build credit may have different priorities from someone who wants rewards on everyday purchases. Likewise, someone carrying an existing balance may care more about the interest rate or introductory balance-transfer terms than travel rewards.
Start by asking yourself:
- Do I want to build or establish credit?
- Do I want cash-back rewards?
- Do I want travel-related rewards?
- Do I need a lower introductory APR?
- Do I expect to carry a balance?
- Do I want a card with no annual fee?
- Do I want a simple card with minimal features?
Having a clear goal makes it easier to eliminate cards that do not match your needs.
Understand Your Credit Profile
Credit cards can have different eligibility requirements. Before applying, understand the general condition of your credit profile.
Factors such as your credit history, existing debt, payment history, income information requested by the issuer and recent applications may affect whether you qualify for a particular card.
Checking your credit reports and understanding your general credit position can help you avoid applying for cards without considering the potential consequences of multiple applications.
Do not assume that a card advertised as a premium product is automatically appropriate for you. Match the card to your financial circumstances instead.
Review Your Spending Habits
Rewards are only useful when they match your normal spending.
Review several months of spending and look for recurring categories such as:
- Groceries
- Restaurants and dining
- Gas or transportation
- Travel
- Online purchases
- Streaming services
- Household expenses
- Recurring bills
If a card offers elevated rewards in a category where you rarely spend, that benefit may have little practical value.
Understand Different Types of Credit Cards
Credit cards can be designed around different purposes. Common categories include:
- Cash-back cards: Designed to return a percentage of eligible purchases as cash rewards or statement credits.
- Travel cards: Often provide points, miles or travel-related benefits.
- Balance-transfer cards: May offer an introductory APR for qualifying balance transfers.
- Low-interest cards: Focus more heavily on ongoing interest costs than rewards.
- Secured cards: Typically require a security deposit and can be designed for people building or rebuilding credit.
- Student cards: Often designed around the needs of eligible students and people establishing credit.
Understanding the purpose of each category helps narrow the search before you compare individual products.
Compare APR
APR or annual percentage rate, is an important number to review before applying.
If you regularly carry a credit card balance from one billing cycle to another, the interest rate can become much more important than rewards.
If you consistently pay your statement balance in full, the ongoing purchase APR may have less practical impact on your normal spending, although it remains important to understand the terms.
Check the Annual Fee
Some credit cards charge an annual fee while others do not.
An annual fee is not automatically bad but you should be able to explain why paying it makes sense for your situation.
For example, a card with a fee may provide rewards or benefits that have meaningful value for a particular cardholder. Another person may receive little benefit and be better served by comparing no-annual-fee options.
Calculate the Break-Even Point
A simple way to evaluate an annual fee is to compare the estimated yearly value of the benefits with the yearly cost.
For example:
| Item | Example Value |
|---|---|
| Estimated annual rewards | $180 |
| Other benefits you would actually use | $70 |
| Total estimated value | $250 |
| Annual fee | $95 |
| Estimated value after fee | $155 |
This is only an example. Actual value depends on the card's current terms and how you personally use its benefits.
Compare Rewards Carefully
Credit card rewards can look attractive but the headline percentage is not the entire story.
When comparing rewards, check:
- Which purchases earn rewards?
- Are rewards capped?
- Are there rotating categories?
- Do rewards expire?
- What redemption options are available?
- Is there a minimum redemption amount?
- Are there special redemption rules?
- Does the card charge an annual fee?
A simple rewards structure may be easier to use than a more complicated system if you do not want to track multiple categories and rotating offers.
Cash Back vs. Points vs. Miles
Cash back is generally straightforward because the reward is usually expressed as a monetary amount.
Points and miles can have different redemption values depending on how they are used. If you are considering a points or miles card, understand the actual redemption options rather than assuming every point has the same value.
Review Other Credit Card Fees
The annual fee is only one potential cost.
Review the card agreement and fee schedule for items such as:
- Balance transfer fees
- Cash advance fees
- Foreign transaction fees
- Late payment fees
- Returned payment fees
- Authorized-user fees
- Other account-related charges
The fees that matter most depend on how you plan to use the card.
Evaluate Introductory Offers
Credit cards sometimes advertise introductory offers involving rewards, spending bonuses or promotional APR periods.
Before focusing on an introductory offer, check:
- How long the introductory period lasts
- How much you must spend to qualify
- Which transactions count toward the requirement
- When the reward is issued
- Whether there are exclusions
- What happens after the introductory period ends
Never spend money you would not otherwise spend simply to qualify for a credit card reward.
Do Not Confuse Introductory APR With Permanent APR
A promotional APR can last for a limited period. The standard APR that applies afterward may be substantially different.
If you are considering a promotional financing offer, know the end date and understand what rate may apply afterward.
Consider the Credit Limit
Your credit limit determines how much you can charge to the account at a given time.
A higher limit does not mean you should spend more. In fact, your budget should determine your spending rather than the available credit limit.
Keeping spending within your financial plan is more important than maximizing the amount of available credit.
Think About Credit Utilization
Credit utilization describes how much of your available revolving credit is being used.
For example, if you have a $5,000 credit limit and a $1,000 balance, the utilization on that account would be 20%.
Credit utilization is one factor used in some credit-scoring models, so understanding your balances and limits can be useful when managing credit.
Check the Issuer's Account Features
A credit card is more than its rewards program. The account management experience can matter too.
Look for features such as:
- Mobile account management
- Transaction alerts
- Payment reminders
- Automatic payments
- Spending notifications
- Card-locking features
- Digital wallet compatibility
- Clear online statements
Features that help you monitor and control the account can be valuable for maintaining good credit habits.
Review Travel and International Features
If you travel internationally, pay particular attention to foreign transaction fees and travel-related features.
Depending on the card, benefits may include travel rewards, travel protections, airport-related benefits or other features. The exact terms vary, so read the current benefit documentation before assigning value to them.
Consider Whether You Actually Need Premium Benefits
Premium credit cards may include numerous benefits but paying for benefits you rarely use can reduce their practical value.
Make a list of the benefits you would realistically use during a typical year. Then compare their potential value with the card's annual cost.
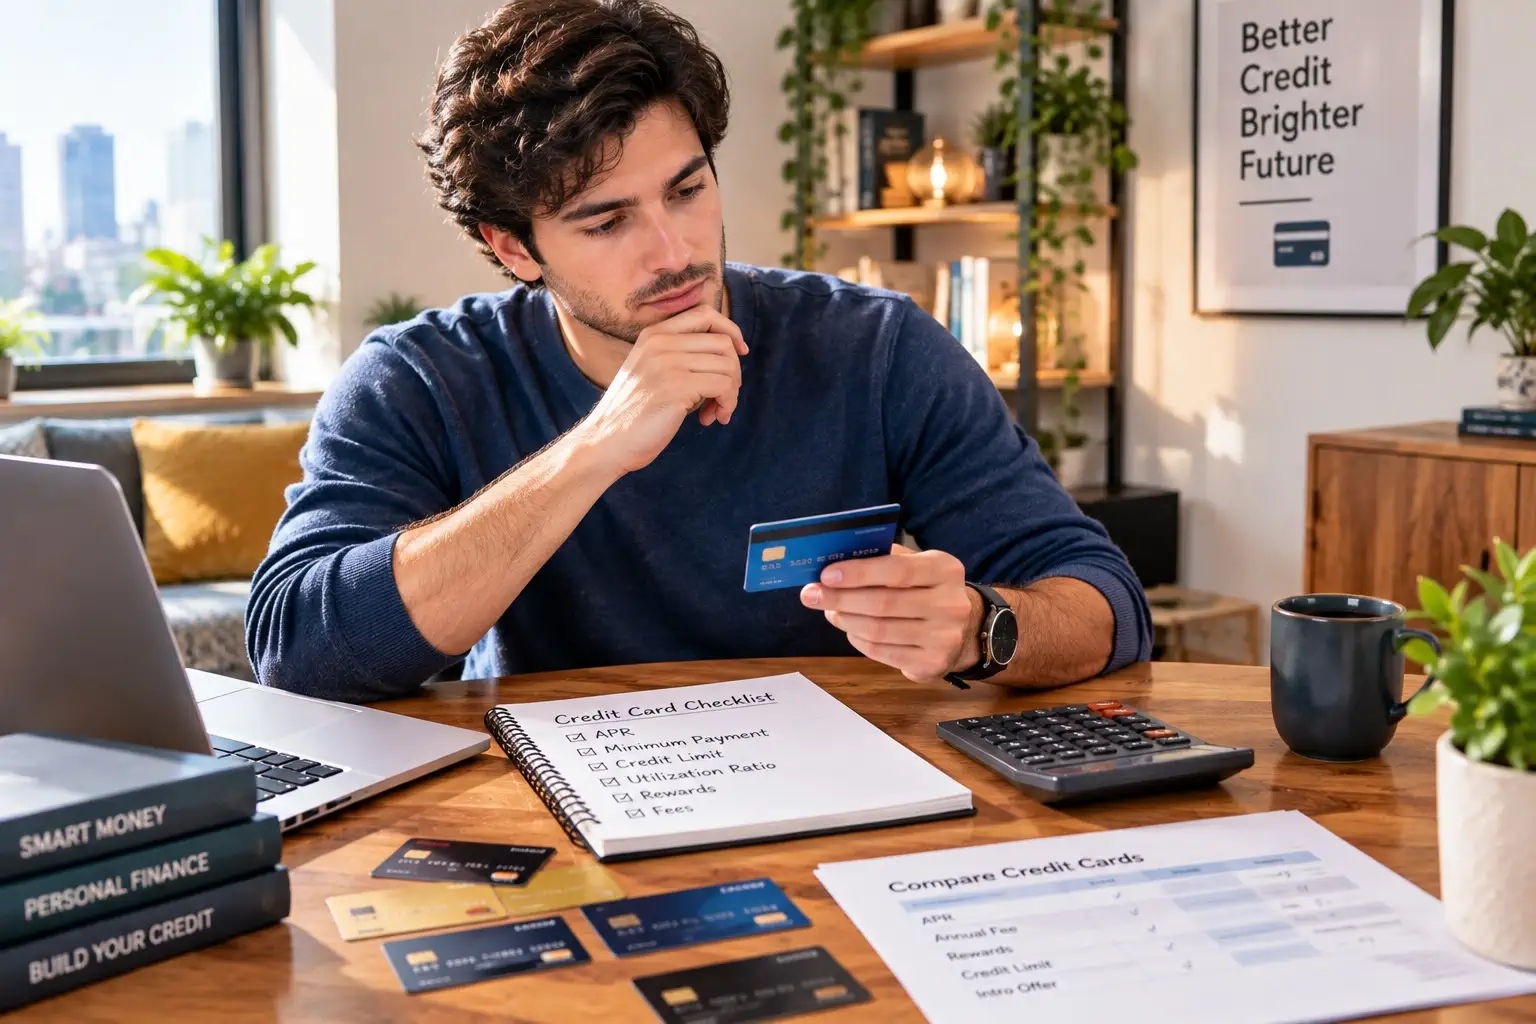
Compare Cards Side by Side
Once you have narrowed your options, create a simple comparison table.
| Feature | Card A | Card B | Card C |
|---|---|---|---|
| Annual fee | $0 | $95 | $0 |
| Rewards | Cash back | Points | Cash back |
| Intro offer | Yes | Yes | No |
| Foreign transaction fee | Check terms | Check terms | Check terms |
| Best fit | Simple rewards | Frequent users | No-fee option |
The numbers above are illustrative rather than descriptions of specific current cards. Always use the issuer's current terms when making a real comparison.
Calculate the Total Potential Cost
Instead of looking at one feature at a time, consider the overall financial picture.
A simple comparison can include:
- Annual fee
- Expected interest costs
- Balance transfer fees
- Foreign transaction fees
- Expected rewards
- Benefits you would actually use
This approach helps prevent a large rewards offer from hiding costs that may be more important to your situation.
Choose Simplicity If You Prefer Simplicity
You do not necessarily need a complicated credit card strategy.
A straightforward card with a simple rewards structure and no annual fee may be easier to manage than a card requiring constant tracking of categories, benefits, transfer partners, and promotional offers.
The best credit card structure for you is the one you can understand and use responsibly.
Think About How You Pay Your Balance
Your payment behavior should play a major role in your decision.
If you normally pay your statement balance in full, rewards and fees may receive more attention in your comparison.
If you regularly carry a balance, interest costs can become much more important. In that situation, a card with attractive rewards may not compensate for significant interest charges.
Never Choose a Card Just Because of a Sign-Up Bonus
Introductory bonuses can be valuable but they should not be the only reason you apply.
Ask whether the card remains useful after the introductory offer ends.
Consider the ongoing fee, rewards structure, APR, benefits and your expected spending after the first few months.
Review the Terms Before Applying
Advertisements often summarize a card's most attractive features. The complete terms contain the details that determine how the account actually works.
Before applying, review:
- Purchase APR
- Balance transfer APR
- Cash advance APR
- Annual fee
- Other applicable fees
- Rewards terms
- Introductory offer terms
- Eligibility information
- Important account restrictions
Pre qualification vs. Applying
Some issuers may offer a pre qualification process that can give you an indication of whether you may qualify without a standard application.
Pre qualification does not necessarily guarantee approval and the exact process varies by issuer.
Understand whether a particular action involves a hard credit inquiry before proceeding.
Do Not Apply for Multiple Cards Without a Plan
Applying for several cards within a short period can result in multiple credit inquiries and new accounts, depending on what you apply for and whether you are approved.
Instead of submitting applications everywhere, narrow your choices first and review the eligibility criteria and terms.
Consider Your Long-Term Use
A credit card is not just an introductory promotion. Think about how the account could fit into your financial system over time.
Ask:
- Will I still use this card in two years?
- Will the annual fee continue to make sense?
- Will the rewards remain useful?
- Will the account be easy to manage?
- Does the card fit my normal spending?
Example: Choosing Between Three Card Types
Imagine three people with different priorities.
| Person | Main Goal | Features to Compare |
|---|---|---|
| Person A | Simple everyday rewards | Cash back, annual fee, reward limits |
| Person B | Travel spending | Travel rewards, fees, redemption options |
| Person C | Lower financing cost | APR, promotional period, fees |
There is no universal card that fits all three situations. Their priorities are different, which is why choosing based on personal circumstances is more useful than simply following a generic list of popular cards.
Credit Card Features That Deserve Extra Attention
When comparing your final options, pay particular attention to features that can have a direct financial impact.
- Ongoing APR
- Annual fee
- Balance transfer terms
- Foreign transaction fees
- Rewards limitations
- Introductory offer requirements
- Credit requirements
- Account management tools
Common Credit Card Selection Mistakes
1. Choosing Only Based on Rewards
Rewards are only one part of the financial equation. Fees and interest can matter more depending on how you use the account.
2. Ignoring the Annual Fee
Always calculate whether the benefits you expect to use justify the annual cost.
3. Focusing Only on the Introductory Offer
Consider the card's ongoing terms after the introductory period ends.
4. Spending More to Earn Rewards
A reward is not a financial benefit if earning it requires unnecessary spending or creates debt you cannot comfortably repay.
5. Ignoring Fees
Review the complete fee schedule instead of looking only at the annual fee.
6. Applying Without Checking the Terms
Read the current offer details and account agreement before submitting an application.
7. Choosing a Card That Is Too Complicated
If you will not use complicated rewards or benefits, a simpler card may be easier to manage.
A Simple Credit Card Comparison Method
You can simplify the process into five steps:
- Define your main goal.
- Review your spending and credit profile.
- Shortlist several cards that fit your needs.
- Compare fees, APR, rewards and benefits.
- Read the current terms before applying.
This method keeps the decision focused on actual financial characteristics instead of marketing language.
How to Choose a Credit Card for Everyday Spending
If your primary use is everyday spending, examine where most of your purchases occur.
Someone who spends heavily on groceries may value a different rewards structure from someone whose largest expenses are travel or transportation.
Compare the rewards categories with your actual spending rather than changing your spending habits simply to earn rewards.
How to Choose a Credit Card for Building Credit
If your goal is establishing or rebuilding credit, focus on manageable account terms and responsible payment behavior.
Consider factors such as:
- Eligibility requirements
- Annual fee
- Security deposit if applicable
- Credit reporting practices
- Account management tools
- Potential path to a different card later
Building credit is primarily about consistent responsible use, not simply opening an account.
How to Choose a Credit Card for Travel
Frequent travelers may want to compare travel rewards and international transaction costs.
Depending on the card, useful features can include travel rewards, transfer options, travel protections and potentially other travel-related benefits.
However, calculate the annual fee and actual value of the benefits based on your travel habits.
How to Choose a Credit Card for a Large Purchase
If you are considering a card because of a large planned purchase, understand the financing terms before applying.
Some cards may have introductory APR offers, while others may simply provide rewards on purchases.
Do not assume an introductory offer means the purchase will be inexpensive overall. Check the promotional period, qualifying requirements and standard APR afterward.
What Matters Most?
There is no single feature that should determine every credit card decision.
The relative importance of each feature depends on how you use credit.
| Your Situation | Features to Pay Attention To |
|---|---|
| Pay balance in full | Rewards, fees, benefits |
| Carry balances | APR and financing terms |
| Building credit | Eligibility, fees, account management |
| Frequent traveler | Travel rewards, fees, travel benefits |
| Simple spending | No-fee structure and easy rewards |
A Practical Final Comparison
Before applying, write down your top three priorities.
For example:
- No annual fee
- Simple cash-back rewards
- Good account management tools
Then compare cards against those priorities. This prevents attractive but irrelevant features from dominating your decision.
Credit Card Selection Checklist
- ☐ I know why I want the card.
- ☐ I reviewed my normal spending.
- ☐ I understand my general credit profile.
- ☐ I compared the APR.
- ☐ I checked the annual fee.
- ☐ I reviewed other applicable fees.
- ☐ I compared the rewards structure.
- ☐ I checked reward limitations.
- ☐ I reviewed introductory offers carefully.
- ☐ I understand what happens after the promotional period.
- ☐ I checked the eligibility requirements.
- ☐ I considered the long-term value.
- ☐ I read the current terms before applying.
Frequently Asked Questions
How do I choose the right credit card?
Start with your financial goal and spending habits. Then compare APR, annual fees, rewards, other fees, introductory offers, eligibility requirements and benefits.
Should I choose a credit card with no annual fee?
A no-annual-fee card can be useful for someone who wants to minimize recurring costs but an annual-fee card may provide benefits that justify the fee for some users. Compare the total expected value rather than the fee alone.
Is a lower APR always better?
A lower APR can matter significantly if you carry a balance. However, APR is only one factor. Fees, rewards, promotional terms and other account features should also be considered.
Should I choose cash back or travel rewards?
It depends on your spending and how you intend to redeem rewards. Cash back is often straightforward, while travel rewards can provide different types of value depending on the program and redemption options.
Should I apply for several credit cards at once?
Avoid applying indiscriminately. Narrow your choices first, review eligibility information and understand that credit applications can involve credit inquiries.
Is a sign-up bonus a good reason to choose a card?
A sign-up bonus can be one factor but it should not be the only reason. Consider whether the card remains useful after the introductory offer ends.
What should I check before applying?
Review the current APR, annual fee, other fees, rewards structure, promotional terms, eligibility information and important account conditions.
Can rewards make a credit card worth an annual fee?
They can for some cardholders but the answer depends on the actual rewards and benefits you expect to use compared with the annual fee and other costs.
Final Thoughts
Choosing a credit card does not have to mean finding the card with the biggest rewards advertisement or the longest list of benefits.
A better approach is to start with your own financial situation, identify what you need from the account and then compare the numbers and terms carefully.
Pay attention to APR, annual fees, rewards, promotional offers, transaction fees, eligibility requirements and the features you will actually use. Most importantly, choose an account that fits your budget and that you can manage responsibly.
The goal is not simply to get another credit card. The goal is to understand the account well enough to use it as part of a healthy financial system.