A budget does not have to mean saying no to everything you enjoy. At its simplest, a budget is a plan for where your money should go before you spend it.
The challenge is that many budgets look perfect on paper but become difficult to follow in real life. An unexpected bill appears. Groceries cost more than expected. A subscription renews. Or you simply have a month where your priorities change.
A useful budget leaves room for real life. It helps you understand your income, plan for essential expenses, save toward meaningful goals and make spending decisions with more confidence.
The best budget is not necessarily the most detailed one. It is the one you can understand, use consistently and adjust when your circumstances change.
What Is a Budget?
A budget is a plan that helps you decide how to use the money you expect to receive during a specific period, usually a month.
Instead of looking at your bank balance and wondering where the money went, a budget gives each major part of your financial life a purpose.
That might include housing, food, transportation, insurance, debt payments, savings, entertainment and other personal expenses.
Your budget does not need to predict every purchase perfectly. Its job is to give you a clear starting plan and help you notice when your actual spending moves away from that plan.
Step 1: Start With Your Income
Before deciding how much you can spend, figure out how much money you realistically have available.
For someone with a predictable paycheck, this may be fairly straightforward. If your income changes from month to month, you may need a more conservative approach.
Focus on money you reasonably expect to have available for the period you are budgeting. Depending on your situation, this could include employment income, freelance income, business income or other regular sources.
If your income varies, avoid building your entire budget around your highest-income month. A more cautious baseline can make your budget easier to manage when income temporarily falls.
Step 2: Track Where Your Money Goes
The next step is to understand your current spending. This is where many people discover that their mental estimate is different from what their transactions actually show.
Review recent bank and credit card activity and group your spending into broad categories. You do not need dozens of categories to get useful information.
Start with categories such as:
- Housing
- Utilities
- Groceries
- Transportation
- Insurance
- Debt payments
- Dining and entertainment
- Shopping and personal expenses
- Savings
Looking at several recent months can also help reveal expenses that do not happen every week but still need to be planned for.
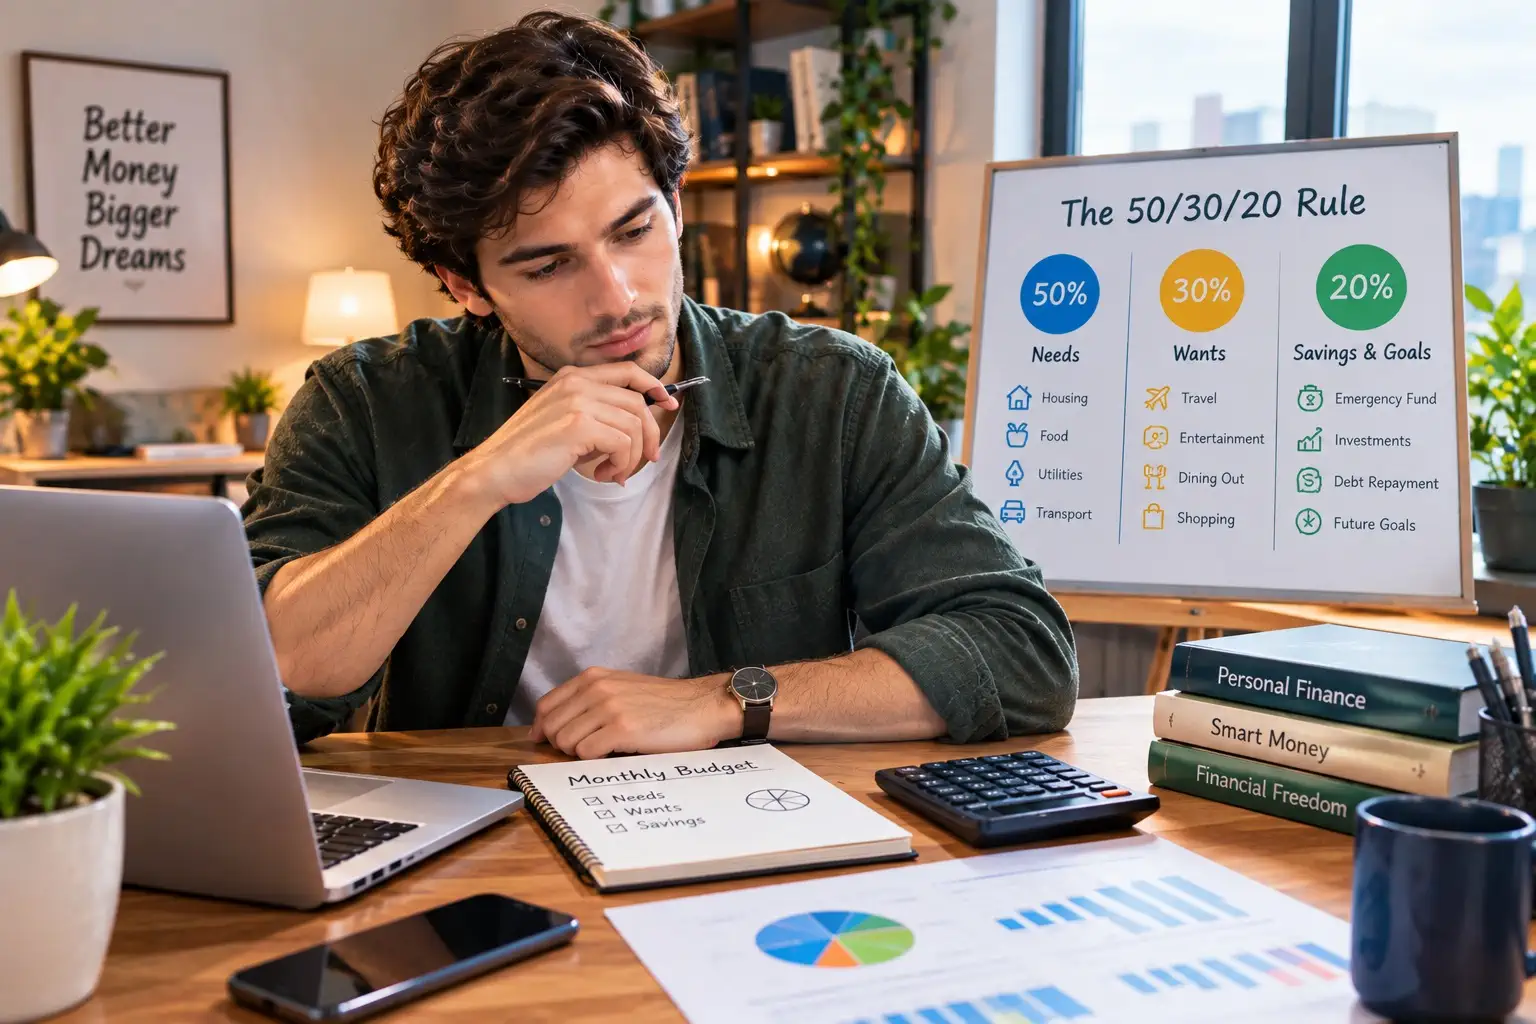
Step 3: Separate Needs, Wants and Goals
Not every expense has the same priority. Separating your spending into broad groups can make budgeting decisions easier.
Needs
These are expenses that are important for maintaining your basic household and financial obligations, such as housing, essential food, utilities, transportation, insurance and required debt payments.
Wants
These are expenses that can improve your lifestyle but may offer more flexibility, such as dining out, entertainment, hobbies, subscriptions or non-essential shopping.
Financial Goals
These are amounts you intentionally set aside for future priorities. Examples can include an emergency fund, a planned purchase, additional debt payments or long-term investing.
The goal is not to eliminate wants. A budget that leaves no room for enjoyment can become difficult to maintain. Instead, decide what matters to you and give those priorities a reasonable place in the plan.
Step 4: Create Practical Budget Categories
Once you understand your income and spending, create a set of categories that is detailed enough to be useful without becoming a chore.
For example, you could organize a monthly budget like this:
| Category | Example Purpose |
|---|---|
| Housing | Rent or mortgage and related household costs |
| Food | Groceries and dining |
| Transportation | Fuel, public transit, parking or vehicle costs |
| Bills | Utilities, phone, internet and recurring services |
| Financial Goals | Savings, investing or additional debt payments |
| Lifestyle | Entertainment, hobbies, shopping and personal spending |
Your categories should reflect your life. Someone who works from home may have very different transportation costs from someone who commutes every day.
Step 5: Give Savings a Place in Your Budget
Savings can easily become whatever money is left at the end of the month. The problem is that there may not be much left.
Instead, treat important savings goals as planned expenses within your budget.
You might create separate targets for:
- Emergency savings
- Short-term purchases
- Annual or seasonal expenses
- Major future goals
- Long-term investing
The amount will depend on your income, obligations and goals. The important part is creating a plan that you can realistically maintain.
Step 6: Plan for Irregular Expenses
One of the easiest ways for a budget to break is to ignore expenses that happen only occasionally.
Annual insurance payments, vehicle maintenance, holidays, school expenses, gifts, travel and home repairs may not appear every month but they can still have a significant impact on your finances.
A useful approach is to estimate the annual cost of an expense and divide it into smaller monthly amounts.
For example, if you expect a $600 annual expense, setting aside $50 per month would create a $600 pool over twelve months.
This approach is often called a sinking fund. It can make large predictable expenses feel much more manageable when they eventually arrive.
Step 7: Review Your Budget Regularly
A budget is not something you create once and never touch again.
Your income can change. Bills can increase. Priorities can shift. A new financial goal may become important.
Consider giving your budget a short review at least once a month.
Ask yourself:
- Did my actual spending match my plan?
- Which category went over budget?
- Was the amount unrealistic or was the spending unusual?
- Did I make progress toward my savings goals?
- Are there subscriptions or expenses I no longer need?
- Does my budget still reflect my priorities?
The purpose of a review is not to criticize yourself. It is to collect information and make the next month's plan more useful.
Common Budgeting Mistakes to Avoid
Even a simple budget can become difficult to maintain when it is built around unrealistic assumptions.
1. Making the budget too complicated
If tracking your spending takes an hour every day, you may eventually stop doing it. Start with broad categories and add detail only when it helps you make better decisions.
2. Forgetting irregular expenses
A budget that only includes monthly bills can look healthy until an annual expense arrives. Plan for predictable non-monthly costs.
3. Leaving out fun spending
Entertainment and personal spending are part of real life. Giving them a reasonable place in the budget can make the overall plan easier to live with.
4. Using unrealistic spending limits
If your grocery budget has been consistently higher than your target, simply writing a smaller number does not automatically change your spending.
Look at your actual history and make gradual changes where possible.
5. Treating one bad month as failure
Unexpected expenses happen. The goal of a budget is not perfection. It is to help you make better decisions over time.
A Simple Monthly Budget Example
Imagine someone has $4,000 available for a monthly budget after taxes and other deductions.
Their plan might look something like this:
| Category | Planned Amount |
|---|---|
| Housing | $1,400 |
| Utilities & Bills | $350 |
| Food | $500 |
| Transportation | $300 |
| Insurance & Other Obligations | $250 |
| Savings & Financial Goals | $700 |
| Lifestyle & Personal | $300 |
| Flexible / Buffer | $200 |
This is only an illustration—not a recommended allocation for everyone. Housing, taxes, insurance, debt, location, family size and personal priorities can make an appropriate budget look very different from one household to another.
The useful idea is the structure: income comes in, important obligations are accounted for, goals receive funding and some flexibility remains for real life.
How to Make Your Budget Easier to Maintain
Creating a budget is only the beginning. The real value comes from using it consistently.
A few small habits can make the process easier.
- Check your accounts regularly.
- Schedule savings transfers when appropriate.
- Review recurring subscriptions.
- Keep a small buffer for unexpected costs.
- Review your budget before major purchases.
- Update the plan when your circumstances change.
You can manage a budget with a spreadsheet, budgeting app, notebook or simple document. The tool matters less than whether the system is easy enough for you to keep using.
Final Thoughts
Creating a budget is really about creating clarity.
You do not need to predict every expense or control every purchase. You simply need a realistic picture of your money and a plan for the priorities that matter most to you.
Start with your income. Look honestly at your spending. Separate essential expenses from flexible ones. Make room for savings and irregular costs. Then review the plan and adjust it as your life changes.
Over time, that simple process can turn a budget from a restrictive list of rules into a practical tool for making more confident financial decisions.
Once you have created your first budget, review your spending after one full month. Use what you learn to make the next version more realistic rather than trying to make the first version perfect.
Related Money Guides